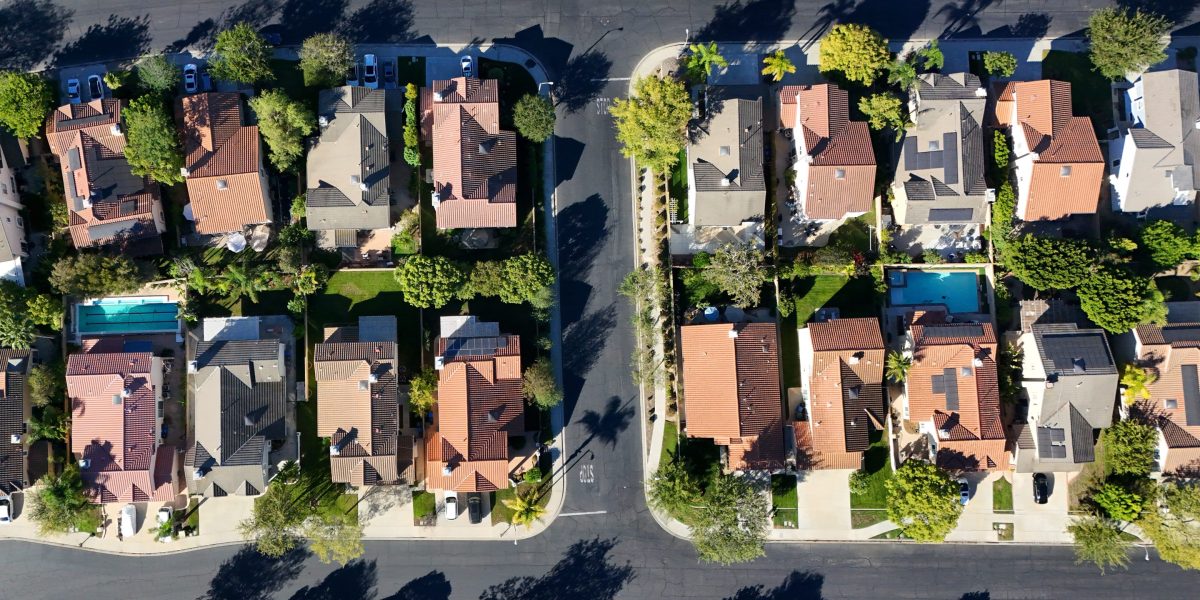
The daily 30-year fixed mortgage rate soared to 7.24% last week, adding yet another cost for homebuyers already facing the double whammy of high housing prices and inflation squeezing their wallets.
Freddie Mac’s weekly average rate also climbed to 6.95%, putting borrowing costs at their highest level since January 2025. The increase comes as the Federal Reserve raised interest rates to combat persistent inflation, adding pressure on borrowing costs across the economy.
The mortgage increase means some families will end up paying hundreds of dollars more per month for a house, according to Brett Johnson, a Colorado-based real estate agent.
“For some buyers, that is enough to push the house they wanted out of their budget,” he told Fortune.
Buyers are hesitating
Americans were already pulling back from the housing market before the latest mortgage rate climb.
Applications for mortgages to purchase a home fell 19% from a year earlier in the week ending on Sept. 11, according to the Mortgage Bankers Association. Even Google searches for “homes for sale” were down 15% from last year, according to real estate brokerage firm Redfin.
Fewer of the buyers who are still looking are committing to a purchase. The number of homes that buyers agreed to buy fell to its lowest level in nearly three years during the four weeks ending Sept. 13, a 5.4% decrease from the year prior, according to Redfin.
Completed home sales are slowing too. Sales of previously owned homes fell 2% in August, the second month in a row they declined, with the yearly sales pace falling below 4 million for the first time since June 2025, according to a National Association of Realtors report.
Together, the numbers show a housing market struggling to turn interested buyers into actual homeowners, and rates approaching 7% could push more of them to delay.
“Debt is getting more expensive, so the American dream of homeownership may be deferred for many right now,” Bess Freedman, CEO of real estate brokerage Brown Harris Stevens, told Fortune.
Home prices are still high, but sellers are losing leverage
Fewer people shopping for homes might make the remaining buyers expect prices to go down, but that hasn’t happened yet on a national scale. Last month, the median existing home sold for $429,100, up 1.6% from a year earlier, according to the same NAR report, though there are signs of some relief in parts of the country. Home prices in the West fell 0.2% from a year earlier, while prices continued to rise in the Northeast, Midwest and South.
“Mortgage rates hovering around 7% are creating more complications for buyers because prices are not coming down,” Freedman said. First-time homebuyers made up less than a third of home sales, according to NAR. Freedman said they’re struggling while buyers with enough cash are “having an easier time.”
Fewer buyers still means more negotiating power for the ones left in the market.
Sellers offered concessions in nearly 45% of U.S. home sales during the three months ending in August, up a few percentage points from a year earlier and the highest share for that period since at least 2020, according to a Redfin analysis. Those concessions include covering closing costs and paying for repairs to get a sale across the finish line.
“When borrowing money is expensive, buyers have less patience for an overpriced house,” Johnson said. “The days of putting a house on the market Friday and having a stack of offers by Monday aren’t something I’d count on right now [for sellers].”
Some sellers are struggling to adjust. Benjamin Schieken, founder of mortgage-shopping platform Fincast, told Fortune he has observed some sellers “pushing back against” the lower listing prices now recommended by their real estate agents.
That gap between what sellers think buyers can afford and what buyers find reasonable can leave a house sitting on the market longer. Schieken said sellers are now pricing homes lower from the start, hoping to attract more buyers and potentially drive the final sale price back up through competing offers.
“There’s a strategic evolution that’s happening here, where home sellers are getting a little bit smarter about where they start the price at and let it get bid back up potentially by bringing more buyers into the mix versus pricing buyers out to begin with,” he said.
This story was originally featured on Fortune.com
Hence then, the article about mortgage rates are nearing 7 delivering another blow to a housing market already losing buyers and facing stalled sales was published today ( ) and is available on Fortune ( Middle East ) The editorial team at PressBee has edited and verified it, and it may have been modified, fully republished, or quoted. You can read and follow the updates of this news or article from its original source.
Read More Details
Finally We wish PressBee provided you with enough information of ( Mortgage rates are nearing 7%, delivering another blow to a housing market already losing buyers and facing stalled sales )
Also on site :
- Dolly Parton Secretly Flew to Germany for Experimental Cancer Treatment Before Death
- Jordan Peele’s Monkeypaw Productions and Universal Film Team With American Cinematheque and Beyond Fest for ‘No Drama’ Initiative (EXCLUSIVE)
- Princess Diana Made Blue Eyeliner Iconic in the ’80s—A Makeup Artist Says This Is the Modern Way To Wear It