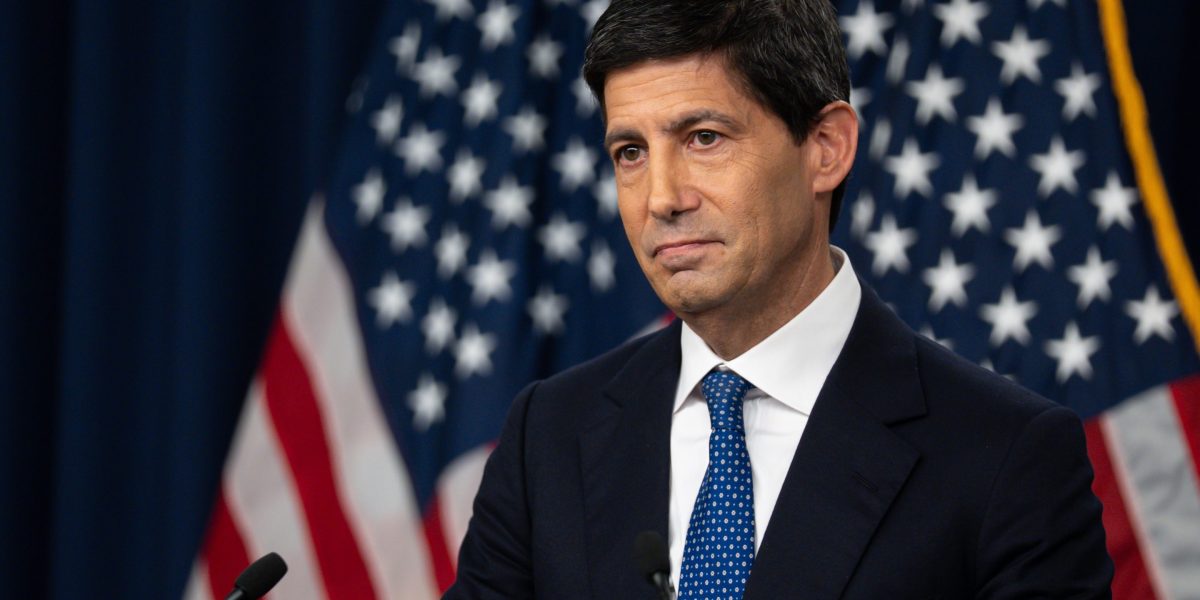
Kevin Warsh may be the most hawkish Federal Reserve chair since Paul Volcker. That’s a compliment in some circles. It’s also a warning. Volcker beat inflation, but he broke things on the way, and the bond market is now finding out what Warsh might break.
Thirty-year Treasury yields have climbed to their highest level since 2002. In September alone, the 10-year yield jumped more than half a percentage point, to about 5.3%. It was the worst month for U.S. government bonds in four years.
The usual explanations don’t hold up for these movements. Technical market dynamics that impact demand may include, for example, a modest slackening in the so-called basis trade (with hedge funds buying fewer Treasurys in support of leveraged bets). Some observers point to an assumed increase in the “term premium” – the extra yield supposedly needed to offset duration risk for holders of longer-term bonds.
Other theories are even more esoteric and/or difficult to measure. There might be an “absorption premium” – an academic suggestion – said to boost the yield for reasons too abstruse to summarize easily. But technical factors seem insufficient to account for a shift of such magnitude in a $40 trillion market. They may play some small role but they are not the drivers of this tectonic regime change.
The strategic explanations would be inflation, deficits and geopolitics, and the “bond vigilantes” who supposedly punish fiscal sin. These are background risks, and nothing in August or September re-priced them.
What changed was the Fed.
How a Speech Became a Rout
Aug. 28: At Jackson Hole, Warsh signals a hawkish turn. Torsten Sløk, Apollo’s chief economist, writes that the Fed “went into 2026 expecting several cuts, and now the FOMC is leaning toward hiking.” The sell-off begins as traders price in a September hike. Sept. 11: A hot August CPI report adds fuel. The sell-off accelerates, though traders may have misread the number. Sept. 16: The Fed raises rates a quarter point, as expected. Warsh’s tone is not expected. He stresses “discipline” and “resolve” and promises that “this Fed will deliver price stability.” The dot plot points to more hikes, with inflation above target until 2029.Markets then priced a string of hikes, with an 80% chance of at least 100 basis points more than before Jackson Hole. “Higher for longer” had become “much higher for much longer.”
Why Traders Panicked
They remember the last time. In 2022–23 the Fed raised rates 525 basis points in 17 months. The Bloomberg Aggregate Index fell 13%. Treasurys lost 12.5%. The 10-year lost 16%, its worst return in a century. The iShares 20+ Year Treasury ETF lost 31.4%.
The damage spread. Mark-to-market losses on “safe” bonds helped kill Silicon Valley Bank and strained the whole banking sector. By mid-2023, banks carried almost $700 billion in unrealized losses, and $300–500 billion remains. Mortgage rates went from 3% to nearly 8%, and the housing “affordability crisis” lingers.
Traders now have a template for an aggressive Fed. They’d rather overreact than underreact.
The Bill So Far
Bonds: The iShares Aggregate bond ETF is down 4% since Jackson Hole. That implies market-wide losses of more than $1 trillion. Banks: My model, built with help from Claude, estimates $115 billion in added unrealized losses in September and $180 billion for the third quarter. That would lift underwater securities more than 50%, to about $500 billion, the highest since June 2024. Housing: Mortgage rates are up almost 100 basis points since Jackson Hole, and home sales are down. The S&P mortgage-backed securities index is off 5%, implying about $400 billion in losses.2026 is not a replay of 2022–23, and the market’s fears may be overdone. But traders burned once have good reason to shed long-duration risk.
Who Pays for “Credibility”
Warsh appears to treat the rout as the price of Fed credibility. His Jackson Hole speech has hit bonds harder, so far, than Ben Bernanke’s 2013 Taper Tantrum did, and that episode is now widely seen as a blunder. The Fed shows no sign of contrition.
Consumers pay, in costlier auto loans and credit cards. Homeowners pay, in higher mortgage payments and a weaker housing market. Businesses pay, in pricier credit. Banks pay, in new losses on “safe” assets. Abroad, higher rates and a stronger dollar strain economies and currencies, and the yen is one example.
That is the Volcker problem. The Fed can win the credibility fight and still lose the people who bear the cost. A chair this hawkish should be asked to prove the price is worth paying.
The opinions expressed in Fortune.com commentary pieces are solely the views of their authors and do not necessarily reflect the opinions and beliefs of Fortune.
This story was originally featured on Fortune.com
Hence then, the article about the hawk fed chair who broke the bond market was published today ( ) and is available on Fortune ( Middle East ) The editorial team at PressBee has edited and verified it, and it may have been modified, fully republished, or quoted. You can read and follow the updates of this news or article from its original source.
Read More Details
Finally We wish PressBee provided you with enough information of ( The hawk Fed Chair who broke the bond market? )
Also on site :
- Sci-Fi Thriller ‘Overstake’ Gets Generative AI Rebuild, Boarded by Cappu Films at Busan Market (EXCLUSIVE)
- In 1931, William Wrigley Jr. built a $1.2 million mansion as a 50th anniversary gift for his wife; it has now sold for $17 million to the Arizona Biltmore’s owner
- Pete Hegseth Welcomes Soldiers Back From Operation Epic Fury in ‘SNL’ Cold Open That Mocks Christa Pike’s Botched Execution and RFK Jr.